For GovCon executives
The financial plan a GovCon executive actually needs
Contract income arrives in lumps, a recompete puts a date on it, and equity carries tax timing nobody explains. Here's how the whole picture gets structured, for owners, presidents and senior leaders across the DMV corridor.
The GovCon executive financial picture
A corporate executive's pay is a salary plus a bonus. A government contractor's pay is a series of awards with end dates, usually a base, a bonus, sometimes deferred compensation, often equity, tied to a recompete decision that isn't yours to make.
That structure changes almost every planning answer. How much reserve is enough. Whether this is the year to max the TSP or the year to hold cash. What a vesting event does to your bracket. Where you should be a resident for tax purposes. When to take the next contract and when to walk away from it.
What actually goes wrong
Rarely the investing. Most GovCon executives we meet are already saving aggressively. What breaks is coordination:
• A reserve sized to a monthly budget rather than a contract cycle, so a gap between awards turns into debt.
• Equity concentrated in one employer, taxed at the wrong moment, or held past the point the risk still made sense.
• Bonuses withheld at the flat supplemental rate, producing a number in April that nobody planned for.
• Federal service and contractor years treated as two separate retirements instead of one income.
• Health coverage that lapses in the gap between contracts, with COBRA as the only plan in place.
How this hub is organized
The six planning areas below are the ones that move the needle for this audience, and each has a guide of its own in the next section. If you read only one, read the reserve piece. It is the number that decides everything else.
The six planning areas a GovCon executive has to coordinate
Each one is manageable on its own. The difficulty is that they touch: a recompete changes your reserve, a vesting event changes your bracket, and a move across the Potomac changes both.
Cash flow and contract reserves
How much cash to hold when your income is a series of awards, and what that reserve has to cover if a contract ends in the middle of a year.
Recompete and transition planning
The decisions made before an award goes the other way: severance and PTO, coverage gaps, 401(k) and equity in transition, and how to compare the offer that follows.
Equity compensation
RSUs, ESPP, options and acquisition stock: when they vest, how they are taxed, and how to keep one company from quietly becoming most of your net worth.
Tax strategy and entity structure
Bonus withholding at the supplemental rate, pass-through income, 1099 decisions and quarterly estimates, coordinated with your CPA rather than guessed at.
Residency across DC, Maryland and Virginia
Where you live and where you work are two different tax questions in the DMV, and getting them wrong is expensive in either direction.
Retirement and federal benefits
FERS, the TSP, a contractor 401(k) and a business interest all have to become one income. That is a coordination problem, not a product problem.
Guides for GovCon executives
Each guide takes one of those six areas and goes all the way through it: the mechanics, the order to do things in, and the mistakes that cost the most. Start with the one that matches what is in front of you.
Retirement Across a Fragmented Career: FERS, TSP and a Contractor 401(k)
A GovCon executive's retirement is rarely one retirement. It's a federal or military career, then a contractor career, then consulting or board work. The work is making them behave like one income.
Read the guide →Where You Live and Where You Work: DC, Maryland and Virginia Tax Residency
An executive can live in Maryland, work in Virginia and sit in DC in the same week. Residency is a question of documented facts, not preference, and it is one of the more consequential details in a GovCon financial life.
Read the guide →Entity Choice, 1099 Income and Quarterly Taxes for GovCon Consultants
Leaving a W-2 role to consult is usually a good decision made with the tax structure as an afterthought. Here's what actually changes, and the order to think about it in.
Read the guide →RSUs, ESPP and Acquisition Equity: What GovCon Executives Get Wrong
Equity is a normal part of executive pay in this industry and is still treated as a bonus. That gap between how it feels and what it is creates most of the mistakes.
Read the guide →Planning for a Recompete, a Layoff or a Shutdown Before It Happens
Recompetes, contract transitions and funding lapses are the normal rhythm of GovCon work, not rare events. Here's the financial sequence to run while there's still time.
Read the guide →How Large a Cash Reserve Should a GovCon Executive Actually Hold?
The three-to-six-month rule assumes a paycheck you can count on. Contract income doesn't behave that way. Here's how to size a reserve to the risk actually sitting in your pipeline.
Read the guide →Is this the right fit?
The fastest way to find out is to read both columns honestly. We turn work down when the answer is no. The call is free either way.
You are likely a good fit if
You have household income above $250K that arrives in uneven amounts, and no one has looked at the whole picture at once.
This may not be the right fit if
Saying so up front saves us both a call.
Questions GovCon executives ask
The four we hear most. If yours isn't here, the intro call is free.
My income is strong this year. Why would I plan around a bad one?
Because your income is a contract, and contracts have end dates. Planning for that is not pessimism. It is what lets you take a risk on the next opportunity, or turn one down, without the decision being made for you.
Should the business pay me a bonus, a distribution, or leave the cash in the company?
That depends on your entity, your bracket and what the cash is actually for. There is a right answer in your situation, and we work it out with your CPA rather than guessing.
I already have a CPA and a 401(k). What would you add?
Coordination. Someone looking at the income, the equity, the benefits and the estate in one place, in an order, at least once a year, instead of each advisor optimizing their own piece of it.
Do you work with owners of GovCon firms, or only executives?
Both. Sole practitioners, partners and owners of firms from a handful of people to a few hundred, plus the executives who run them. The planning issues are the same; the scale is not.
Ryan P. McGonigal
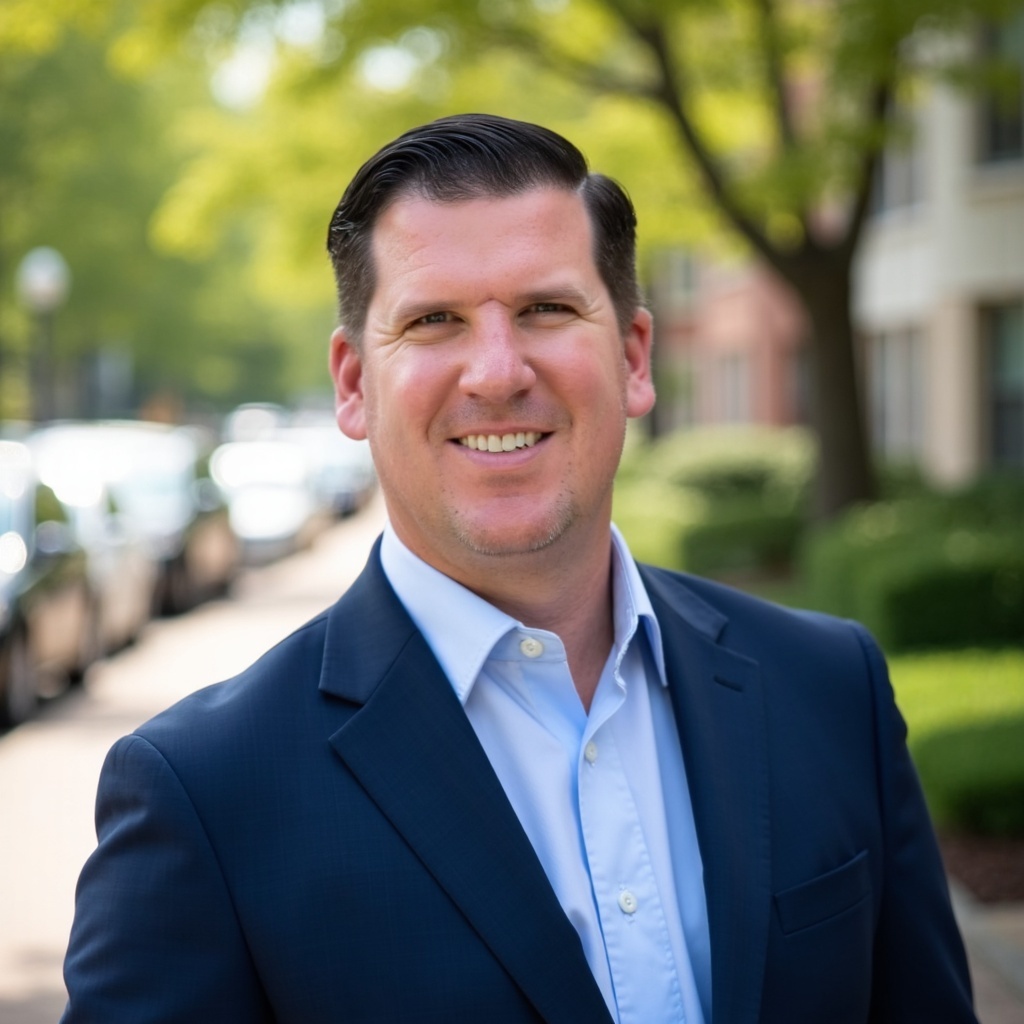
Ryan has worked in financial services since 1999 and founded RPM Financial Group in Rockville, Maryland in 2022. He built the practice around the clients whose pay and benefits do not fit a standard plan: federal employees, government contractors and cleared professionals. He is a planner, not a tax preparer or an attorney, and works alongside each client's CPA.
• 25+ years in financial services, working with clients since 1999
• Planning delivered through RightCapital; LPL Financial is Broker/Dealer & RIA
• Advisory accounts managed at SEI, and estate documents through the Trust & Will partnership
Stop putting this off.
You have been meaning to get a real financial plan in place for a while. The longer you wait, the more expensive and complicated the catch-up becomes. Book a free 20-minute call.
No commitment, no sales pitch.